Showing posts with label IPO Updates. Show all posts

IPO Update –Cantabil Retail India Ltd.

Dressed up for the Show

cantabil Cantabil has eneterd the capital markets with an offering of shares in the price band of Rs.127-135 to garner 105 crores for its expansion plans.

Positives

1. Cantabil has a network of 411 exclusive retail outlets spread across India of which 141 outlets are exclusively for its brand “La Fanso” an rest for “Cantabil” brand.

2. It offers complete range of formal wear, party wear and casual wear for Men, Women and Kids .

Concerns

1. Cantabil depends on third parties for a considerable portion of sales as well as manufacturing  of its products. It makes it vulnerable to performance issues.

2. Centralization of manufacturing facilities at Delhi exposes company to issues related to local unrest or disturbances.

3. The apparel segment has many established players and hence the company has intense competition on this front to keep its brand value flying high. Some of the competitors include Raymonds, Gini and Jony, Provogue,Koutons and Arvind brands.

Financials

Cantabil posted a Topline of Rs. 263.6 crores for year ending March.2010 and a profit after tax of Rs. 14.68 crores. Company’s revenues and profit have grown significantly over past four years as it added the Women and Kids wears as a part of its offerings.

Valuations

At the upper band of the offer price, the company is seeking a PE multiple of more than 15 while peers like Koutons is quoting at PE of 12 and Kewal Kiran at 14 times. The issue seems fully priced as compared to its peers. However, the booming markets may still put premium on listing. I am planning to put some token money to taste the waters.

Issue Opens : 22-09-2010

Issue Closes: 27-09-2010

Registrar: Beetal Financial & Computer services

Current Grey market premium : Rs.12

Read More!

IPO Update : Electrosteel Steels Limited

New Baby in the world of Steel

electro I have nothing exciting to write about this new kid on the block. The company is promoted by Electrosteel Castings Limited , which is a leader in Cast Iron pipes and Ductile Iron Spun pipes and I could find this as the only silver lining.

The company is in the process of setting up 2.2 MTPA Steel plant in the state of Jharkhand. It does not have any operating history. It will take a couple of years for the operating performance of the company to unfold and hence I would prefer to avoid the IPO. Only those investor who would like to take a long term view may think of applying at the lower band of the offer price.

Registrar : Karvy Computershare

Issue Closes : 24-Sep-2010

Read More!

IPO Update: Eros International media limited

Full Entertainment for Investors too !

eros_logo Eros International IPO is offering shares @ 158-175 to raise up to Rs. 350 crore. A quick look at the positives and concerns.


Positives

1. Eros has a content library of over 1000 films and the company is yet to milk these effectively.

2. Diversity and segmentation of revenue- Eros derives revenue from Theatre release of new movies, sale to channels and music rights. Further a large portion of revenue is generated from overseas releases which ensures good geographical segmentation.

 
Concerns

1. Failure to provide super hit movies in future may turn the tide.

2. Not competent to make its own movies. The only production “Aa dekhen Zara” was a big flop.

On valuations the issue is priced at a PE of 21 on the higher end which is in line with valuation enjoyed by peers such as UTV software. With good going of “Dabang” and few good movies lined up for release the stock is all set to provide full entertainment to investors on the stock markets too . I am applying with a view to book listing gains.

Current Grey Market Premium :  Rs. 35

Registrar : Link Intime

Issue Closes : 21-Sep-2010

Read More!

IPO Update : Career Point Infosystems

cp_logo This IPO may not be comparable to the likes of Everonn Edu which has given 400% return since its listing and it may not repeat the euphoria created by Educomp solution since its listing, but Career Point info systems definitely offer a opportunity to participate in a public offering of a new class of business – Education –Tutorials.

At the same time it also presents a potential risk as we do not have a comparable listed entity. The company needs no introduction as neither Kota as a hub for engineering tutorials. It provides tutorial services to high school and post high school students for various competitive entrance examinations including AIEEE,IIT-JEE, PMT and PDT through its 17 company operated and 16 Franchisee centres.


Positives

1. Being first issue of its kind of a education tutorial company, the IPO will set precedent for the other companies in this sector who aspire to get listed.

2. The education tutorial has been a highly un-organized industry and the listing of career point will enable people to have shareholding in such companies as education is considered to be a highly lucrative and promising industry.

3. Career point has earned a good brand name in its field. In education sector, reputation matters a lot and the company is poised to reap benefit of the same.

4. Presence across 13 states provides Career point an edge to target the wide consumer base of students preparing for the engineering exams.

5. The company plans to foray aggressively into ECAMS (Education consultancy and management services) and is exploring to extend it to private-public schools as well as government school.

6. The company also runs Global public school and Career point University.


Concerns

1. Education industry witness rapid changes and with ever increasing competition it would a challenge for the company to maintain its competitive edge.

2. The company has a history of negative Cash flows from Operating and Investing activities on account of its rapid expansion plans.

3. A search and seizure operation was carried at company premises and premises of the promoters last year by income tax department. One of the promoter had accepted unaccounted income of the company, promoters and relatives of INR 60 Million. There were series of notices served on the company by other departments based on above . The management needs to show more honesty and transparency and better standards of corporate governance as they serve the industry which runs on credibility.

4. The training center at Kota contributes more than 58% of  revenue and hence any disruption of any sort at Kota may lead to significant loss of revenue for the company.


Financials & Valuations

Career point reported a Top-line of Rs. 65.8 crore for year ending 31-Mar-2010, up 37% against last year. Net profit stood at 17.8 Crores, up 18.7% against last year. As per a recent interview, the management has shown confidence of a growth rate of 25% .

The EPS for year ending Mar-10 stood at 14.71 and the Return of net worth stood at 14.6%. At the upper price band of 310, the PE works out to be 28 which is aggressive considering Everonn trading at current PE of around 21 and Educomp at a PE of 25. The stock is quoting at a premium of Rs . 90 in Grey market .

I am considering applying for the IPO and if the stocks lists at a good premium, I plan to book listing gains.

Issue Opens : September 16,2010

Issue Closes: September 21,2010

Registrar : Link Intime

Read More!

IPO Update: Indiabulls Power Ltd.

In Quest for Power “full” India

indiabullspowerlogo Indiabuls Power Ltd. has entered the capital markets with an issue of 33.98 Crore shares of Rs. 10 each at a price band of Rs. 40-45 per share. Investment Guru is of the view that India Bulls is just another player trying to leverage the India Power Story like Adani, Reliance and Tatas. The company is currently in the process of setting up its power plants will take 3-4 years to start commercial operations. It’s a story similar to Adani power and hence it’s more of a long term play.

  • The Company is a subsidiary of IBREL, a part of the Indiabulls Group.
  • IBPL is currently executing five power projects: 1,320 MW Amravati Power Project – Phase I, 1,335 MW Nashik Power Project, 1,320 MW Bhaiyathan Power Project, 1320 MW Amravati Power Project – Phase II and 1320 MW Chhattisgarh Power Project.
  • The company expects to sell 75 per cent of the power generation via a long-term power purchase agreement (PPA) and balance through trading of power.
  • Since the company has not yet commenced the operations, there is no financial performance to compare with other players.
  • The projects are expected to be funded through a D/E ratio of 75:25.
  • It is also developing four medium size Hydro Power Projects in Arunachal Pradesh aggregating to 167 MW. Indiabulls has also entered into MoUs with the Govt. of Madhya Pradesh and Jharkhand for setting up of 2640 MW & 1320 MW Thermal Power Projects in each of these States respectively.

Investment Guru is of the view that we have already seen what happened to the Adani and NHPC issues and there is no reason why Indiabulls should get different treatment. The stock is currently commanding a premium of Rs. 4-5 in grey markets but for that matter even Adani commanded a premium in grey matter. This is a pure long term play and the stock will become dull after listing sensations until news of developments on the operational front starts coming in. For those who are looking for listing gains, if the promoters decide to price at a lower band , you can look for a 10% gain otherwise you would have to pray for your luck .

Read More!

OIL India : Listing Strategy

OIL India is going to list on NSE and BSE on Wednesday,30th September,2009.
There was a good response from QIB and HNI segment. However, the retail segment was oversubscribed 1.76 times. The Current Grey market premium for Oil India is in the range of Rs. 50-60.

Investment Guru is of the view that the stock may list at a modest premium of Rs. 50-100 against its issue price of Rs. 1050. Though the fundamentals of the company are quite strong, it has the inherent limitations of sharing of Subsidy Burden and inadequate geographical spread which would keep a tab on its performance. Though the company has a impressive track record on On-shore drilling, it has yet to prove its expertise in off-shore segment. Read More!

IPO Update : Jindal Cotex Ltd.

Too pricey to fit the bill – Avoid

Company : Jindal Cotex Ltd.

Issue Price : Rs. 70 – 75

Outlook : Avoid

About Jindal Cotex

Jindal cotex is engaged in the business of manufacturing of Acrylic, Polyester, and Polyester- Viscose, Polyester Cotton, combed and carded yarns, which are appropriate for apparels, suitings & knitted fabrics. Company has current installed capacity of 23,472 spindles for acrylic, cotton blended and polyester yarns. It manufacture and sell yarns under the trade name ‘JINDAL’.

 
Objects of the Issue

The Company is setting up a new facility to manufacture cotton yarn with a capacity of 28,800 spindles in Ludhiana in Phase I.

It will further add 21600 Spindles, Yarn dyeing facility and a Garment unit with capacity of 3000 pcs. per day in Phase II.

The company would use the funds to invest in Subsidiary Jindal Medicot which manufactures Medical Textile products. It would also invest in another subsidiary Jindal Specialty textiles which manufactures PVC Laminated products.

Financials

The company has put up an impressive top-line growth of 39% for year ended 31st March,2009. However the same momentum was not visible in the bottom line which grew only by 2.3% which suggest that operating cost increased in much bigger proportion.

 
Overall Assessment

The company is a again a classical case of greedy promoters who are asking for more than their  worth. This a trend visible in Indian markets that as the stock markets gain momentum the promoters start flooding the capital markets with issue at a aggressive premium. I strongly believe that market regulators should do something about it in the interest of at least retail investors.

Coming back to Jindal cotex, the company is asking investors to invest at a Pre issue P/E of 20.23 at lower band and 21.68 at the upper band while the Industry average is just 9.10

Investment Guru is of view that investors should give this IPO a miss.

Read More!

NHPC IPO Allotment Status & Listing Strategy

nhpclogo NHPC IPO allotment status is out. Click Here to check your application status. NHPC IPO got overwhelming response similar to that of Adani power. The IPO got subscribed 23.5 times with retail segment subscribed by around 3.8 times. NHPC basis of allotment can be seen in table below. Though both Adani and NHPC IPO’s have generated tremendous response from the QIB segment, the retail oversubscription has been moderate and shows that IPO investors are still shy in applying for the IPO’s.
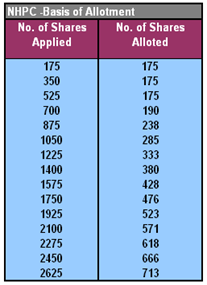
nhpc boa

The lukewarm or say powerless listing of Adani power has actually validated the fears of retail Investors. Both Adani and NHPC IPO’s were considered to be priced aggressively and Adani stock has already been punished. Now is it turn of NHPC IPO ? Let’s see. NHPC stock is expected to list in first week of September.

Government has fixed NHPC offer price at Rs. 36 per share, i.e., on the higher band of the offer price. Prior to listing of Adani power, the Grey market premium of NHPC was quoting at Rs. 12-14 per share. However, the latest grey market premium is in the range of Rs. 4-5 which shows that listing for NHPC might be lackluster.

NHPC is the largest Hydro power generator in the country with substantial experience in design, development, execution and operation of Hydro-Electric Projects (HEP). The company has 13 HEP plants in operation with an installed capacity of 5,175 MW. It is currently undertaking construction of 11 HEP plants with a total installed capacity of 4,622 MW and 8 of these projects totaling 1492 MW are scheduled for completion by the year 2011-12. NHPC generated 16,582 Million Units (MUs) in 2008-09 as against 14,811 MUs in 2007-08.

On consolidated basis, NHPC reported an Operating Income (OI) of Rs 34.94 billion and Profit After Tax (PAT - excluding minority interest) of Rs 12.44 billion in 2008-09 as against an OI of Rs 29.31 billion and PAT of Rs 12.07 billion in 2007-08.

NHPC’s projects are located in India’s Northern and North-Eastern regions, which have favorable hydro resources, thereby ensuring sufficient water availability for power generation. There has been comparison between NTPC and NHPC over the valuations but one clear advantage that NHPC has is that its operation does not have fuel requirement unlike NTPC which makes its operating cost very competitive.

Another advantage of NHPC is that not only are its plants located in High energy deficit areas which ensures consistent demand, NHPC sale of Electricity is backed by LC’s from banks which can be used in case of delay in payments. Further, it is supported by a tripartite agreement between the customer state,RBI and GoI, whereby NHPC can recover the payments from the central plan assistance given to the state by GoI. As a result of these measures, NHPC, for the last few years has reported almost 100% collections against the billing to the respective states.

On the Risk aspects, NHPC projects have long gestation period and hence the the proposed projects would start operating only from 2010-11 onwards. Talking of the Financials, NHPC ROCE stands at 10.18% and RONW stands at just 6.58% due to its large equity base.

Investment Guru’s overall assessment is that NHPC is a stock which may provide good returns over long term (2 Years time frame) based on its fundamentals. The stock may list in the range of Rs. 39-42 and may remain in this range from short term perspective.

Update: NHPC is going to list on NSE and BSE on Tuesday, 1st September,2009

Read More!

ASBA- Welcome step for IPO Investors

Gone are the days when IPO investors had to worry about getting back their refunds in time and loosing on the interest income for the money they invested in the IPO during the period from application to getting back the refund. SEBI has introduced the mechanism of ASBA which would act as a right step in providing relief to the IPO investors from worries of delay in refunds and loss of interest income.


What is ASBA ?

asba ASBA means “Application Supported by Blocked amount”. ASBA is an application containing an authorization to block the application money in the bank account, for subscribing to an issue. If an investor is applying through ASBA, his application money shall be debited from the bank account only if his/her application is selected for allotment after the basis of allotment is finalized, or the issue is withdrawn/failed.

To put it in more simpler words, when you apply for an IPO now,  you don’t have to pay the amount upfront. You just give an instruction to the bank to block the amount in your bank account to the extent of your application amount. So you don’t pay anything to the company. The application amount remains in your bank account and you continue to earn interest on it . The hold will be released once the allotment is made by the company. If you have got allotment, the amount to the extent of shares allotted would be debited to your account and the hold on balance of amount would be released. You cannot withdraw the amount of money blocked against an IPO application till the blocked amount is released on allotment/refund.

Currently the facility is available only to IPO’s with Book Building route. SEBI has issued a list of Self Certified Syndicate Banks (SCSB) who are authorized to accept ASAB application forms. Currently 10 banks have enrolled for providing this facility. Others are expected to enroll soon.

For those who apply for IPO through Online trading and their Banks are classified as SCSB, the option of applying through ASBA has been activated by default so you don’t need to take any additional steps.

Detailed Guideline from SEBI

List of SCSB’s

Read More!

Adani Power- IPO Allotment & Listing Strategy

If you have applied for the Adani Power IPO, by now you would have become owner of this yet to be operational power generation company which is part of Adani Group. Check Allotment Status for Adani Power.

 adani_logo The Adani IPO has brought life back to the ailing primary markets. It has received tremendous response from the Qualified Institutional Buyers who have shown huge apatite for the stock. The QIB portion was subscribed more than 39 times. The Retail Investor segment got oversubscribed by just 3 times. A similar pattern was also seen in NHPC IPO. This trend shows that retail investor has still not come out openly and is still licking the old wounds caused by turmoil in stock markets as well as dismal performance of IPO’s. However, on a positive note it shows that the interest in primary markets is building back and it speaks of better prospects for the upcoming issues.

adani basis ipo

Another thing which was quite evident from the subscription pattern was that the investing community rates India as a good investment opportunity and in particular the pace at which  infrastructure reforms are expected to take place has aroused significant interest in Power sector. In India the generation of power is far less than the demand which is estimated to rise at  a far greater rate than in last 5 years.

According to the 17th Electric Power Survey, India’s peak demand will reach approximately 152,746 MW with an energy requirement of approximately 968 billion units by fiscal year 2012. By the fiscal year 2017, peak demand is expected to reach 218,209 MW with an energy requirement of 1,392 billion units. Currently we have a Peak Availability of just 97,669 MW. This shows the tremendous scope available to companies in power sector.


Listing Strategy for Adani Power

The stock is expected to list on August 20th,2009. We have been hearing a lot about overpricing of the IPO by the Adani’s. Whether the issue was overpriced or not will be finally decided by the markets. The company has not started operations yet and hence doesn’t have any earnings data.  At Rs 100 per share the company would quote at a Price to Book Value of 2.8. NTPC, an existing profit making company is currently priced at 2.8 times its Book Value. This shows that Adani Power has been priced aggressively. However, one should remember the fact that Adani has certain impressive operational advantages such as location of projects in areas where peak time shortages is maximum, leverage of  presence of Adani group in Coal mining, Shipping as well as power trading.

From a long term prospective the stock looks very promising. However from the current perspective the stock is priced aggressively. The current grey market premium is ruling at  Rs. 8-10. The stock is expected to list in the range of  Rs 110-115 and may go up or down depending on the buying by the QIB’s to cover for the shortfall in allotment.  Investment Guru is of the view that Investors may book profits at a price above Rs 115 and take advantage of listing euphoria. Long term Investors can re-enter the stock at lower levels once the listing sensation is over.

Read More!

IPO’s continue to haunt Investors

The heartthrobs of Year 2007 and some part of 2008, IPO’s are no longer common Investor’s attractive hub. IPO’s that have listed in Year 2009 have the same story to tell. See for yourself. 

ipo2009

There are companies who have deferred their plan to float IPO’s due to the current turmoil in the market. Bharat Oman Refineries, Photon Infotech and NHPC are among the companies who have deferred their IPO plans. Other companies who have filed the DRHP include Mayajaal Entertainment, Pradip Overseas, Sea TV Network, Great Eastern Energy Corporation & Texmo Pipes and products.

Read More!

IPO Update: Nu Tek India

Sustaining growth a challenge – Avoid it

Nu Tek India has entered the capital markets with an offer of 44 Lac shares at a price band of Rs. 179-192. Investment Guru is of the view that Investors should avoid the IPO on account of following reasons:

  • Nu tek is operating in a very competitive segment and has limitation of scale of operations.

  • In view of above, it would not be possible for the company to sustain its growth rate of over 47%. The growing trend of Infrastructure sharing by telecom companies would also act as a restraint.

  • The issue is priced at a PE of 15.6 which looks aggressive considering the current market scenario. Since the issue is small it may sail through, but it may not provide listing gains to the investors unless there is change of sentiment at the time of listing. The listing trend of recent IPO’s is sufficient to deter investors from applying blindly to the IPO’s. See my post on Initial profit-less option

  • The business model is skewed towards limited customers.

  • Large players have significant advantage in securing large scale orders and hence Nu tek faces serious challenge with regards to competitors like GTL who enjoy better presence and have better financial and technical competencies.

Issue opens : 29-Jul-2008
Issue Closes : 01-Aug-2008
Registrar : Aarthi consultants
Related Information
About the company
Company Fact Sheet
Company's Strength
Check IPO Allotment Status of NuTek

Read More!

IPO's make a dent in Investor's Coffers

IPO: Initial Profit-less Option

The Year 2008 has so far been a nightmare for investors who have put in their money in the IPO’s. Out of the 22 IPO’s which have been listed during this year, 18 are currently trading at a loss ranging from 2% to 69%. Only 4 IPO’s have managed to swim against the current and trade above their Issue price. Companies like Emaar and Wockhardt had to withdraw their IPO’s.


As a general rule , IPO’s do not do well in the bearish markets. But there were a huge queue of companies who have planned to line up their IPO’s during the dream run on the bourses, but most of them have shelved their plans given the massacre post January. However, few needy ones have shown courage to roll it despite the ongoing state of markets. And to their advantage, they found investor who subscribed to their offerings. Most of these companies have priced their IPO’s on the higher side of the price band even after knowing very well that the investor may not fetch good price post listing.


Investment Guru is of the view that it’s still not the right time to subscribe to IPO’s since the secondary markets sentiments are extremely negative and hence one should forget the hefty premium that these IPO’s used to give till 6 month back. When the best of listed companies are not doing well on the stock market, how can we expect the IPO’s to do well and that too at a premium.

Read More!

Reliance Power : Basis of Allotment

Reliance Power: Allotment Status and basis of Allotment

The wait is finally over. The allotment status of Reliance power IPO is out and you can check the same by clicking the link below or on the IPO Allotment Pane on the right hand side.

Reliance Power IPO Allotment Status

Basis of Allotment


The current Grey market premium for Reliance Power is in the range of Rs. 150-180 Read More!

IPO Update : Reliance Power payment Options

As per the latest data available on NSE website the Reliance power IPO has been oversubscribed by 23 times by now. Money control says that the Retail portion has been subscribed 6 times. We were discussing in yesterday's post about the payment option to be chosen for applying to reliance power IPO. Now since we have more clarity on the subscription data , it looks that applying through part payment option would be a good idea as your capital investmnet would be lesser ensuring higher return on your investment.

However, it is sad to say that the company has not clarified if it going to allot fully paid up shares to those applying for partly paid up shares in case of oversubscription. So the clouds of uncertainty are still there. The company reserves the right to allot you partly paid shares and call for the balance amount at a later date stipulated in the prospectus. Hence, one may not get shares before listing and may be reduced to a mere viewer seeing others booking listing gains. So if you are willing to take the risk choose the option of part payment. But if you want to be on doubly sure that you sell on listing day, paying full amount is a safe option. I am going to take a risk and apply through partly paid option. Meanwhile Grey market is qouting a premium in the range of Rs. 290-310 on the offer price of Rs. 450 with hardly any takers at that premium. Read More!

Reliance Power - In "Name" lies the Power


Dear friends, you must have heard a lot on Reliance power IPO and why not, there is an unprecedented euphoria for this IPO. Ask anybody and the reply will be – “Reliance Power- Yes, I am going to apply for it”. This is called the power of Name or say power of brand Value. You can sell a rock for a price of diamond if it is sold in the name “Reliance” and yes such brands are not created in days. It has taken late Sh. Dhiru Bhai Ambani a life time to create this brand and such is the magic of the brand that a project which is going to be up and running only in 2010 can ask a massive premium and that too with a expectation of it doubling on the listing day. So who says “Naam mein Kya rakha hai ?”

I am not going to write an IPO update sort of thing on reliance power. Why ? because I don’t think anybody would like to read me on whether they should apply for it or not! But I would like to dwelve on some questions that this IPO has raised.


Is Reliance Power going the RPL way?

Yes, the IPO of Reliance Power has something in common with that of Reliance Petroleum apart from fact that both are from “Reliance” stable. Investors have seen what happened to RPL post listing. Reliance Power is similar to RPL since it is not going to generate revenues till 2010. So, what does this convey ? This conveys that once the listing euphoria is over, the scrip will be dependent on news on the progress of its projects to move up or down and will be quite volatile with downward bias. I am not sure if you agree with me or not but Anil Ambani does not stand anywhere near the execution intelligence of big brother Mukesh Ambani and the they way the various projects of Reliance power are lined up, it would be an uphill task for Junior Ambani to withstand the trust of the investors. Let’s hope for the best.


Should One apply for fully paid or partly paid ?

This has been a bit confusing part for the investors. Company has provided two options. Option”A” where the investors can apply for fully paid up share. In this case they have to pay Rs. 430 (as Rs. 20 discount for Retail Investors) per share at the time of application.

Under Option “B” the investors can apply for partly paid shares. In this case they have to pay only 25% of the share price. The company will make a call for the balance amount post listing and the investors have to pay the balance amount at that point of time. In this case the investors will not be able to sell on the listing day since they will have only partly paid shares.

Now there is a catch. The company reserves the right to adjust the refund payable to the investors against the partly paid shares and issue fully paid up shares. In this case these investors would also get fully paid up shares and can sell them on listing.

Now the mathematics is that if the retail portion gets oversubscribed by more than 4 times (which it surely will) the partly paid investors will also be issued fully paid up shares and the refund due on their application will be adjusted towards the balance payment. In that case it would be advisable to apply for partly paid shares. If any friend has any information contrary to this please let us know by leaving a comment.


Reliance Power Website

Check Allotment Status of
Reliance Power IPO Read More!

IPO Allotment Status : Jyothy Laboratories

Jyothi Laboratories - IPO Allotment Status

Click her to Check Allotment Status of Jyothi laboratories IPO

The stock was offered to investors @ Rs. 690 and the grey market is putting a premium of Rs 200 on the offer price.

Meanwhile Both BGR Energy (100 x)and Transformers and Rectifiers (82 x) IPO have been hugely oversubscribed on the closing day. Read More!

IPO Update : Brigade Enterprise Limited

Banking on Bangaluru

Brigade enterpise limited has entered the capital markets with an offer of 166.24 lac shares of Rs. 10 each at a price band of Rs. 351-390 per share. Investment Guru is of the view that realty and infrastructure sector would continue to be in limelight as it makes deeper inroads in the world of stock markets. Brigade enterprise’s business model comprises of a mix of residential, commercial and hospitality properties. The company’s operation and land bank are focused in and around Bangalore. Exposure of the company to a limited geographical area and a lean land reserve of just 44.16 million square feet might put a dent on the margins in future.

However, the bright side of the picture is that the company has sizeable ongoing projects which would keep the scorecard ticking in the medium term. On valuations parameters the stock looks aggresively priced leaving little scope of appreciation for Investors. The issue also has a green-shoe clause which would be used to provide stability to the price of the stock for one month if the market price falls below the issue price. Investors should consider subscribing to the issue purely from listing gains perspective. For long term perspective, there are better players available in the secondary markets with sizeable land bank and better geographical spread.

Issue highlights

  • BEL is a real estate development company based in Bangalore, primarily focused on the development of residential, commercial and hospitality properties in South India. Company’s residential properties include
    integrated lifestyle enclaves and apartment buildings targeted towards middle income and high income customers.

  • The company has completed a total of 67 properties, comprising of 41 residential properties, 21 commercial properties and five hospitality properties, aggregating to approximately 5.67 million sq. ft. of Saleable Area and approximately 6.74 million sq. ft. of Developable Area.

  • The company is currently developing 16 properties, including Brigade Gateway and Brigade Metropolis, which are integrated lifestyle enclaves and that comprise of a combined Saleable Area of approximately 10.83 million sq. ft. and a combined Developable Area of approximately 11.89 million sq. ft.

  • Consolidated total income was Rs. 4,170.20 million for the fiscal year 2007 as compared to Rs.2,032.32 million for the fiscal year 2006 and Rs. 1,605.03 million for the fiscal year 2005, representing year over year increases of 105.19%, 26.62% and 109.38%, respectively.

  • The consolidated profit after tax was Rs. 714.98 million for the fiscal year 2007 as compared to Rs. 423.06 million for the fiscal year 2006 and Rs. 198.77 million for the fiscal year 2005, representing year over year increases of 69.00%, 112.84% and 85.06%, respectively.

  • Return on Net worth is 47%. Net Asset value is 26.52 per share.

Issue Opens : December10, 2007
Issue Closes: December13, 2007
Registrar : Karvy Computershare

Click Here to check IPO Allotment Status of Brigade Enterprise Ltd.

Read More!

IPO Update: Transformers & Rectifiers India Limited

Transforming the power equation

TRIL has entered the capital markets with a public issue of 29.95 Lac shares of Rs. 10 each at a price band of Rs. 425-465 per share through book building process. Investment Guru is of the view that Power transmission and distribution is an integral part of the power sector’s growth story and Transformers play a pivotal role in this process. TRIL is one of the major players in this segment.

However, in this case too the promoters have not left much on the table for the investors as similar companies are available at same valuations in the secondary markets. One can apply for the issue with a view of moderate listing gains on listing. However, from a medium term perspective investment in peers such as Indo-tech transformers is also advisable as the company is operating on better margins.


Let’s take a look at the company

  • TRIL is one of the major players in the Indian markets manufacturing a wide range of transformers ranging from power generation, transmission and distribution transformers, industrial transformers and a wide range of speciality transformers.

  • TRIL manufacture transformers upto 220 kV Class, having an installed capacity of 7,200 MVA transformers per annum.

  • The company currently operate through two manufacturing units, located at Changodar, near Ahmedabad and Odhav, in Ahmedabad, both in Gujarat

  • Key customers include utilities and power transmission companies. The company has also exported transformers to countries such as the England, Canada, United Arab Emirates, South Africa, Saudi Arabia and Indonesia.

  • Company’s business strategy is to focus on manufacturing of high capacity transformers at the proposed manufacturing facility at Moraiya since high capacity transformers command better margins.

  • The company intends to leverage its relationships with the power transmission companies to take up turnkey projects for setting up sub stations.

  • TRIL has a healthy order book position of Rs.319 crore as on September 1, 2007 with most of the contracts having an embedded price variation clause, shielding the company from adverse movement in prices of key raw materials like copper and steel. TRIL has strong in- house design capabilities which is a key success factor for this industry as transformers are custom built as per the requirements of the customer.

  • CARE has assigned a 'CARE IPO Grade 4' to the IPO which indicates above average fundamentals.

  • Power transformers constituted 77% of total sales of the company in FY07 followed by furnace transformers (13%) and others (10%). Sales to State electricity utilities constituted 51% of total sales of TRIL for FY07 with the remaining to industrial and other sectors.

  • During FY07, TRIL's total income grew by 69% over FY06 on account of increase in sales volume as well as per mva realisations. The company was able to sell higher mva (80 and above) transformers in FY07 as compared to FY06, where margins are better.

  • TRIL's PAT margin also improved to 7.99% in FY07 as compared to 5.8% in FY06. ROCE and RONW were high at 62% and 54% in YQ7 as compared to 42% and 43% in FY06 respectively.

  • EPS for the six months ended September,2007 (annualized) is Rs. 20.4 (post issue equity) which translates into a PE multiple of 23.

  • Return on Net Worth is 41.36 % for FY07.

Issue Opens : December 7, 2007
Issue closes: December 12, 2007
Registrar: Intime Spectrum

Click here to check IPO Allotment Status of TRIL

Read More!

IPO Update: BGR Energy Systems Limited

Electrifying Business at Sky High Pricing

BGR Energy systems has entered the capital markets with a public issue of 91.36 Lac shares at a price band of Rs. 425-480. Investment Guru is of the view that the company is into the powerful business of Power equipments and hence has potential to deliver excellent performance given its unique business proposition, government’s thrust on this sector and the demand supply mismatch.

However, the promoters have been greedy in pricing the issue and the issue at the higher band is asking for a valuation in line with those of Blue-chips like BHEL and L&T. ICRA has assigned Grade 3 to the issue indicating Average fundamentals. I would prefer to stay away from the issue (though it is commanding a premium in grey market even at this aggresive pricing) since the current fundamentals do not justify such a high valuation and I would not like to pay a price today for the three year forward earnings of the company given the risk factors (see below). I would suggest that investors with long term view or high risk takers should only invest in the issue.

What’s Good about BGR Energy ?

  • The company is well placed in its business of power projects which provides turnkey Engineering, procurement and construction (EPC) and Balance of plant (BOP) services given the limited players in the space and huge business opportunities due to focus on power sector.

  • BGR plans to open a marketing office in Dubai to ensure proximity to clients and to open a manufacturing facility in China to expand manufacturing capabilities.

  • Company boasts of a strong order book of Rs. 33212 million which brings visibility to its earnings.

  • The company has in house designing and engineering capabilities which provide significant cost advantage.

  • BGR has a proven track record of executing 130 contracts in 42 countries in Asia, Middle east, Africa and Eurpoe.

  • The company has come along way from a subcontractor to securing direct orders from power generation companies.

  • The company has posted a strong growth in both top line and bottom line over past two years. For the Quarter ended 30th June the company posted a top line of Rs.239 crore and Net Profit of 17 crores.

  • The company has carried out Pre IPO placement of its shares to CVC (20.88 Lac shares) and Reliance Capital (14.4 lac shares) at a price of Rs.450.

  • The issue proceeds would be utilized in augmenting the working capital and establishing manufacturing and assembling facilities.

  • The company generates a Return on Net worth of 39% which is higher than that of L&T and BHEL.

What’s not good about BGR Energy ?

  • The company is dependant on few customers for a major chunk of its revenue. The Top three clients contributed 48% of the topline.

  • Major chunk of the revenue (73%) comes from its business with government entities and hence the business is prone to delays in execution of the projects based on political developments and changes in budgetary allocations.

  • The company has a very high account receivable collection cycle (as high as 180 days). This puts a burden on the working capital position of the company and could be a limiting factor in optimizing the operational and financial efficiencies.

  • Pricing Risks – Most of the projects executed by the company are on a fixed price basis. For 18 months ending 31st March 2007, 90% of the total income was derived from fixed price contracts. Though the company enters into back to back contracts from suppliers, pressure on margins due to rise in input costs cannot be ruled out and would adversely impact the company’s performance.

  • The annualized EPS on the results posted for Quarter ending 30th June,2007 stood at 9.7 which translates into a PE multiple of 50. This makes the issue priced in line with valuation of much stronger, capable and dependable companies like L&T and BHEL.

  • The Net asset value per share comes to 12.8 which shows that the IPO price is 37.5 times its Net asset value. This makes issue quite expensive.

Issue Opens : December 5, 2007
Issue Closes : December 12, 2007
Registrar : Intime Spectrum

You can check BGR Energy IPO Allotment Status here. Read More!