Stock Review : Uttam Galva Steel

Will Mittal factor change the fortunes for Uttam Steel ?

Stock : Uttam Galva Steel

CMP : 113

Book Value: 71.04

EPS (Trailing) : 9.49

As the performance of the stock suggest, Markets had a clue about it ! Uttam steel has already risen by 83% in just One month.  The stock has more than doubled in last 3 months. So what’s the buzz !!!  Global Steel King L.N. Mittal is making a debut in India by acquiring 35% stake in Uttam Steel.

Mittal’s company Arcelor Mittal is all set to become the Co-promoter of the company. The promoters have signed an agreement to sell 5.6% stake in Uttam steel.  Arcelor Mittal will launch an open offer on September 7 to acquire balance 29.4% stake in the company. Mittal is offering a price of Rs. 120 per share for acquiring this stake.

If the offer by Mittal remains unsubscribed, the promoters would transfer further stake to Mittal so that both have equal stake in the company.


How will this deal help Uttam Steel ?

Apart from giving foothold to Arcelor Mittal in Indian Steel sector, the deal would be a facelift for Uttam steel. The association with Mittal is surely going to be big boost to the brand name of Uttam steel.

Uttam steel is set to get better availability of Raw Material. The company already sources around 50% of its raw material from Arcelor Mittal.

It will also have an opportunity to transform itself from a galvanized steel producer to a integrated Steel major. It will have access to latest technology from Arcelor Mittal and access to new product segments and geographies.


Demerger of Power Biz

Another important development is that recently  the Bombay high court has sanctioned the scheme of arrangement between Uttam steel and power and Uttam Galva Steel for the demerger of the power division of Uttam Steel and power into the company. The Scheme has got effective from 21st August,2009.

The demerger of power division will help separate listing of this entity and help shareholders to unlock the value of their investment in the company.


Current Financials

For the Year ended 31st March, 2009 company posted a top line of Rs. 4372 Crore and Net profit of 100 Crore.  Though this was a growth of  over 38% over last year, the profit were lower by 24 Crore on account of high interest outgo and higher operating costs.

Uttam steel clocked a turnover of 1073 Crore for the first quarter of the current year and a Net profit of 34.57 Crore.

Investment Guru is of the view that both the developments i.e., Acquisition of 35% stake by Arcelor Mittal @ 120 per share and Demerger of power division hold good omen for the company and would not only boost its brand image but also enable it to log a impressive growth in coming years.

Read More!

IPO Update : Jindal Cotex Ltd.

Too pricey to fit the bill – Avoid

Company : Jindal Cotex Ltd.

Issue Price : Rs. 70 – 75

Outlook : Avoid

About Jindal Cotex

Jindal cotex is engaged in the business of manufacturing of Acrylic, Polyester, and Polyester- Viscose, Polyester Cotton, combed and carded yarns, which are appropriate for apparels, suitings & knitted fabrics. Company has current installed capacity of 23,472 spindles for acrylic, cotton blended and polyester yarns. It manufacture and sell yarns under the trade name ‘JINDAL’.

 
Objects of the Issue

The Company is setting up a new facility to manufacture cotton yarn with a capacity of 28,800 spindles in Ludhiana in Phase I.

It will further add 21600 Spindles, Yarn dyeing facility and a Garment unit with capacity of 3000 pcs. per day in Phase II.

The company would use the funds to invest in Subsidiary Jindal Medicot which manufactures Medical Textile products. It would also invest in another subsidiary Jindal Specialty textiles which manufactures PVC Laminated products.

Financials

The company has put up an impressive top-line growth of 39% for year ended 31st March,2009. However the same momentum was not visible in the bottom line which grew only by 2.3% which suggest that operating cost increased in much bigger proportion.

 
Overall Assessment

The company is a again a classical case of greedy promoters who are asking for more than their  worth. This a trend visible in Indian markets that as the stock markets gain momentum the promoters start flooding the capital markets with issue at a aggressive premium. I strongly believe that market regulators should do something about it in the interest of at least retail investors.

Coming back to Jindal cotex, the company is asking investors to invest at a Pre issue P/E of 20.23 at lower band and 21.68 at the upper band while the Industry average is just 9.10

Investment Guru is of view that investors should give this IPO a miss.

Read More!

NHPC IPO Allotment Status & Listing Strategy

nhpclogo NHPC IPO allotment status is out. Click Here to check your application status. NHPC IPO got overwhelming response similar to that of Adani power. The IPO got subscribed 23.5 times with retail segment subscribed by around 3.8 times. NHPC basis of allotment can be seen in table below. Though both Adani and NHPC IPO’s have generated tremendous response from the QIB segment, the retail oversubscription has been moderate and shows that IPO investors are still shy in applying for the IPO’s.
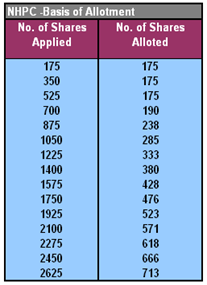
nhpc boa

The lukewarm or say powerless listing of Adani power has actually validated the fears of retail Investors. Both Adani and NHPC IPO’s were considered to be priced aggressively and Adani stock has already been punished. Now is it turn of NHPC IPO ? Let’s see. NHPC stock is expected to list in first week of September.

Government has fixed NHPC offer price at Rs. 36 per share, i.e., on the higher band of the offer price. Prior to listing of Adani power, the Grey market premium of NHPC was quoting at Rs. 12-14 per share. However, the latest grey market premium is in the range of Rs. 4-5 which shows that listing for NHPC might be lackluster.

NHPC is the largest Hydro power generator in the country with substantial experience in design, development, execution and operation of Hydro-Electric Projects (HEP). The company has 13 HEP plants in operation with an installed capacity of 5,175 MW. It is currently undertaking construction of 11 HEP plants with a total installed capacity of 4,622 MW and 8 of these projects totaling 1492 MW are scheduled for completion by the year 2011-12. NHPC generated 16,582 Million Units (MUs) in 2008-09 as against 14,811 MUs in 2007-08.

On consolidated basis, NHPC reported an Operating Income (OI) of Rs 34.94 billion and Profit After Tax (PAT - excluding minority interest) of Rs 12.44 billion in 2008-09 as against an OI of Rs 29.31 billion and PAT of Rs 12.07 billion in 2007-08.

NHPC’s projects are located in India’s Northern and North-Eastern regions, which have favorable hydro resources, thereby ensuring sufficient water availability for power generation. There has been comparison between NTPC and NHPC over the valuations but one clear advantage that NHPC has is that its operation does not have fuel requirement unlike NTPC which makes its operating cost very competitive.

Another advantage of NHPC is that not only are its plants located in High energy deficit areas which ensures consistent demand, NHPC sale of Electricity is backed by LC’s from banks which can be used in case of delay in payments. Further, it is supported by a tripartite agreement between the customer state,RBI and GoI, whereby NHPC can recover the payments from the central plan assistance given to the state by GoI. As a result of these measures, NHPC, for the last few years has reported almost 100% collections against the billing to the respective states.

On the Risk aspects, NHPC projects have long gestation period and hence the the proposed projects would start operating only from 2010-11 onwards. Talking of the Financials, NHPC ROCE stands at 10.18% and RONW stands at just 6.58% due to its large equity base.

Investment Guru’s overall assessment is that NHPC is a stock which may provide good returns over long term (2 Years time frame) based on its fundamentals. The stock may list in the range of Rs. 39-42 and may remain in this range from short term perspective.

Update: NHPC is going to list on NSE and BSE on Tuesday, 1st September,2009

Read More!

File your ITR-V form till 30th September,2009

The Income Tax department has extended the time limit for filing of ITR-V form.  The ITR-V form relating to returns which have been filed electronically (without digital signature) on or after 1st April, 2009 can now be filed on or before the 30th September, 2009 or within a period of 60 days of uploading of the electronic return data, whichever is later.

The ITR-V should continue to be sent by ordinary post to Post Bag No.1, Electronic City Post Office, Bengaluru, Karnataka-560100.

To assist taxpayers, a limited call center service with two agents has been established at ITD-CPC, Bengaluru. Taxpayer queries on status of ITR-V receipt at CPC, Bengaluru will be answered on 080-43456700 between 9:30 AM to 6 PM between Monday to Friday. The service will be available in English, Hindi and Kannada.


Check your E-filing Processing Status online

If you have e-filed your Income tax return and have already submitted the ITR-V through ordinary post, you might be interested in checking the status of your e-filing. Now you can login in to your account on Income Tax department website and check the status of your filing.

Go to https://incometaxindiaefiling.gov.in/portal/index.jsp

Log ton to your account using your PAN No. and password.

Once you log in Go to “ MY Accounts”

In “My Accounts” you will find a option of “E-Filing Processing Status”…Click this.

e-file

Now enter your E-filing Acknowledgement number (This can be found from the ITR-V form that was generated when you uploaded your return online. A copy of the same was also sent to the email Id mentioned in your return) and Assessment Year to get the status of your ITR-V form.


You can also call up  the Call center numbers given above to find status of your ITR-V submission.

Read More!

Stock Review: South Indian Bank

siblogo

Stock : South Indian Bank

CMP: Rs 108.5    Book Value : Rs 113.76

Industry : Banking – Private Sector


Creation of the Swadeshi movement in India to help the business community from the clutches of greedy moneylenders, South Indian Bank has travelled a long distance in converging itself to a next generation banking destination.

Investment Guru is of the view that South Indian Bank is a good buy from short term as well as medium to long term perspective.

  • SIB has put up a good show on a consistent basis. The advances have grown from Rs 5300 Crore  to 11800 Crore in last 4 years.
  • Interest Income has grown at a CAGR of 33.5% over the period of last 4 years.
  • SIB has also shown consistent growth in net profits with a CAGR of 100% over last 3 years.
  • The stock offers an attractive dividend yield 2.78% in addition to growth prospects which creates a good combination for investors.
  • SIB commands strong brand loyalty among its NRI customers.
  • With EPS of 19.14 the stock is currently quoting at a Price to Book Value of 0.95 and a PE of 5.64 which shows that the stock has a strong potential to move up based on its recent performance as compared to its peers which are quoting between PE multiples of  8 to as high as 35.
  • The Q1’09 results of the bank were encouraging with bank reporting 60 Crore Net profit and quarterly EPS of 5.32. Net NPA’s fell to 0.39% as compared to 0.49% recorded in Q1’08.
  • FII’s hold 36.22% stake in the company as compared to 42.7% last year. However, there is no promoter holding which is partly a reason for comparative lower valuations assigned to the bank. On the other hand, this makes it a hostile takeover target and provides investor a possibility of windfall gains if that happens.
Read More!

ASBA- Welcome step for IPO Investors

Gone are the days when IPO investors had to worry about getting back their refunds in time and loosing on the interest income for the money they invested in the IPO during the period from application to getting back the refund. SEBI has introduced the mechanism of ASBA which would act as a right step in providing relief to the IPO investors from worries of delay in refunds and loss of interest income.


What is ASBA ?

asba ASBA means “Application Supported by Blocked amount”. ASBA is an application containing an authorization to block the application money in the bank account, for subscribing to an issue. If an investor is applying through ASBA, his application money shall be debited from the bank account only if his/her application is selected for allotment after the basis of allotment is finalized, or the issue is withdrawn/failed.

To put it in more simpler words, when you apply for an IPO now,  you don’t have to pay the amount upfront. You just give an instruction to the bank to block the amount in your bank account to the extent of your application amount. So you don’t pay anything to the company. The application amount remains in your bank account and you continue to earn interest on it . The hold will be released once the allotment is made by the company. If you have got allotment, the amount to the extent of shares allotted would be debited to your account and the hold on balance of amount would be released. You cannot withdraw the amount of money blocked against an IPO application till the blocked amount is released on allotment/refund.

Currently the facility is available only to IPO’s with Book Building route. SEBI has issued a list of Self Certified Syndicate Banks (SCSB) who are authorized to accept ASAB application forms. Currently 10 banks have enrolled for providing this facility. Others are expected to enroll soon.

For those who apply for IPO through Online trading and their Banks are classified as SCSB, the option of applying through ASBA has been activated by default so you don’t need to take any additional steps.

Detailed Guideline from SEBI

List of SCSB’s

Read More!