IPO Update: Indiabulls Power Ltd.

In Quest for Power “full” India

indiabullspowerlogo Indiabuls Power Ltd. has entered the capital markets with an issue of 33.98 Crore shares of Rs. 10 each at a price band of Rs. 40-45 per share. Investment Guru is of the view that India Bulls is just another player trying to leverage the India Power Story like Adani, Reliance and Tatas. The company is currently in the process of setting up its power plants will take 3-4 years to start commercial operations. It’s a story similar to Adani power and hence it’s more of a long term play.

  • The Company is a subsidiary of IBREL, a part of the Indiabulls Group.
  • IBPL is currently executing five power projects: 1,320 MW Amravati Power Project – Phase I, 1,335 MW Nashik Power Project, 1,320 MW Bhaiyathan Power Project, 1320 MW Amravati Power Project – Phase II and 1320 MW Chhattisgarh Power Project.
  • The company expects to sell 75 per cent of the power generation via a long-term power purchase agreement (PPA) and balance through trading of power.
  • Since the company has not yet commenced the operations, there is no financial performance to compare with other players.
  • The projects are expected to be funded through a D/E ratio of 75:25.
  • It is also developing four medium size Hydro Power Projects in Arunachal Pradesh aggregating to 167 MW. Indiabulls has also entered into MoUs with the Govt. of Madhya Pradesh and Jharkhand for setting up of 2640 MW & 1320 MW Thermal Power Projects in each of these States respectively.

Investment Guru is of the view that we have already seen what happened to the Adani and NHPC issues and there is no reason why Indiabulls should get different treatment. The stock is currently commanding a premium of Rs. 4-5 in grey markets but for that matter even Adani commanded a premium in grey matter. This is a pure long term play and the stock will become dull after listing sensations until news of developments on the operational front starts coming in. For those who are looking for listing gains, if the promoters decide to price at a lower band , you can look for a 10% gain otherwise you would have to pray for your luck .

Read More!

Reliance declares 1:1 Bonus and Rs.13 Dividend

ril For those who thought that days are gone for this once evergreen stock , it’s time to be taken aback. Reliance Industries has added to the diwali celebrations of its shareholders by announcing a combo of a liberal 1:1 Bonus issue (after a gap of 12 years) and Rs. 13 per share dividend.


What does this Bonus means for Reliance Shareholders ?

  • The Bonus issue is an attempt by Reliance Industries to instill confidence in the shareholders towards the tradition of this company to bestow Investor friendly measures.
  • Bonus Issues doesn’t change anything in terms of Financial performance & fundamentals of the company and hence is EPS neutral. However, it does have an indirect impact in terms of improving the sentiments for the stock and brings in more liquidity. Historically , we have seen run up in the stocks after Bonus announcements and stocks have given better returns post Bonus adjusted prices. So, essentially, it is a sentiment booster measure.
  • The timing cannot be more right for the company to announce a bonus as the stock price of reliance Industries has been a laggard as compared to sensex performance due to the ongoing tussle between Mukesh Ambani and his younger brother Anil Ambani over the Gas supply pact. The Bonus issue will provide some impetus to the investor sentiments which was clouded by the ongoing dispute.
  • The Bonus issue has been on account of two major milestones achieved by the company i.e., successful commencement of Gas production from its KG6 Basin and building of new refinery at reliance Petroleum.
  • The Bonus issue is also applicable to shareholders of Reliance Petroleum shares pursuant to recent amalgamation of the company with RIL. The company has fixed Record date of 29th September for reckoning the members entitled to receive 1 Share of Reliance Industries for every 16 Shares held in Reliance Petroleum.
  • The Record date for Bonus has not been announced yet.
Read More!

OIL India : Listing Strategy

OIL India is going to list on NSE and BSE on Wednesday,30th September,2009.
There was a good response from QIB and HNI segment. However, the retail segment was oversubscribed 1.76 times. The Current Grey market premium for Oil India is in the range of Rs. 50-60.

Investment Guru is of the view that the stock may list at a modest premium of Rs. 50-100 against its issue price of Rs. 1050. Though the fundamentals of the company are quite strong, it has the inherent limitations of sharing of Subsidy Burden and inadequate geographical spread which would keep a tab on its performance. Though the company has a impressive track record on On-shore drilling, it has yet to prove its expertise in off-shore segment. Read More!

Stock Review : Uttam Galva Steel

Will Mittal factor change the fortunes for Uttam Steel ?

Stock : Uttam Galva Steel

CMP : 113

Book Value: 71.04

EPS (Trailing) : 9.49

As the performance of the stock suggest, Markets had a clue about it ! Uttam steel has already risen by 83% in just One month.  The stock has more than doubled in last 3 months. So what’s the buzz !!!  Global Steel King L.N. Mittal is making a debut in India by acquiring 35% stake in Uttam Steel.

Mittal’s company Arcelor Mittal is all set to become the Co-promoter of the company. The promoters have signed an agreement to sell 5.6% stake in Uttam steel.  Arcelor Mittal will launch an open offer on September 7 to acquire balance 29.4% stake in the company. Mittal is offering a price of Rs. 120 per share for acquiring this stake.

If the offer by Mittal remains unsubscribed, the promoters would transfer further stake to Mittal so that both have equal stake in the company.


How will this deal help Uttam Steel ?

Apart from giving foothold to Arcelor Mittal in Indian Steel sector, the deal would be a facelift for Uttam steel. The association with Mittal is surely going to be big boost to the brand name of Uttam steel.

Uttam steel is set to get better availability of Raw Material. The company already sources around 50% of its raw material from Arcelor Mittal.

It will also have an opportunity to transform itself from a galvanized steel producer to a integrated Steel major. It will have access to latest technology from Arcelor Mittal and access to new product segments and geographies.


Demerger of Power Biz

Another important development is that recently  the Bombay high court has sanctioned the scheme of arrangement between Uttam steel and power and Uttam Galva Steel for the demerger of the power division of Uttam Steel and power into the company. The Scheme has got effective from 21st August,2009.

The demerger of power division will help separate listing of this entity and help shareholders to unlock the value of their investment in the company.


Current Financials

For the Year ended 31st March, 2009 company posted a top line of Rs. 4372 Crore and Net profit of 100 Crore.  Though this was a growth of  over 38% over last year, the profit were lower by 24 Crore on account of high interest outgo and higher operating costs.

Uttam steel clocked a turnover of 1073 Crore for the first quarter of the current year and a Net profit of 34.57 Crore.

Investment Guru is of the view that both the developments i.e., Acquisition of 35% stake by Arcelor Mittal @ 120 per share and Demerger of power division hold good omen for the company and would not only boost its brand image but also enable it to log a impressive growth in coming years.

Read More!

IPO Update : Jindal Cotex Ltd.

Too pricey to fit the bill – Avoid

Company : Jindal Cotex Ltd.

Issue Price : Rs. 70 – 75

Outlook : Avoid

About Jindal Cotex

Jindal cotex is engaged in the business of manufacturing of Acrylic, Polyester, and Polyester- Viscose, Polyester Cotton, combed and carded yarns, which are appropriate for apparels, suitings & knitted fabrics. Company has current installed capacity of 23,472 spindles for acrylic, cotton blended and polyester yarns. It manufacture and sell yarns under the trade name ‘JINDAL’.

 
Objects of the Issue

The Company is setting up a new facility to manufacture cotton yarn with a capacity of 28,800 spindles in Ludhiana in Phase I.

It will further add 21600 Spindles, Yarn dyeing facility and a Garment unit with capacity of 3000 pcs. per day in Phase II.

The company would use the funds to invest in Subsidiary Jindal Medicot which manufactures Medical Textile products. It would also invest in another subsidiary Jindal Specialty textiles which manufactures PVC Laminated products.

Financials

The company has put up an impressive top-line growth of 39% for year ended 31st March,2009. However the same momentum was not visible in the bottom line which grew only by 2.3% which suggest that operating cost increased in much bigger proportion.

 
Overall Assessment

The company is a again a classical case of greedy promoters who are asking for more than their  worth. This a trend visible in Indian markets that as the stock markets gain momentum the promoters start flooding the capital markets with issue at a aggressive premium. I strongly believe that market regulators should do something about it in the interest of at least retail investors.

Coming back to Jindal cotex, the company is asking investors to invest at a Pre issue P/E of 20.23 at lower band and 21.68 at the upper band while the Industry average is just 9.10

Investment Guru is of view that investors should give this IPO a miss.

Read More!

NHPC IPO Allotment Status & Listing Strategy

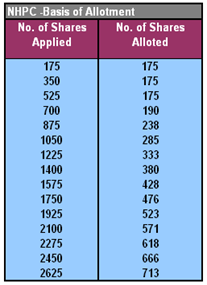
nhpclogo NHPC IPO allotment status is out. Click Here to check your application status. NHPC IPO got overwhelming response similar to that of Adani power. The IPO got subscribed 23.5 times with retail segment subscribed by around 3.8 times. NHPC basis of allotment can be seen in table below. Though both Adani and NHPC IPO’s have generated tremendous response from the QIB segment, the retail oversubscription has been moderate and shows that IPO investors are still shy in applying for the IPO’s.
nhpc boa

The lukewarm or say powerless listing of Adani power has actually validated the fears of retail Investors. Both Adani and NHPC IPO’s were considered to be priced aggressively and Adani stock has already been punished. Now is it turn of NHPC IPO ? Let’s see. NHPC stock is expected to list in first week of September.

Government has fixed NHPC offer price at Rs. 36 per share, i.e., on the higher band of the offer price. Prior to listing of Adani power, the Grey market premium of NHPC was quoting at Rs. 12-14 per share. However, the latest grey market premium is in the range of Rs. 4-5 which shows that listing for NHPC might be lackluster.

NHPC is the largest Hydro power generator in the country with substantial experience in design, development, execution and operation of Hydro-Electric Projects (HEP). The company has 13 HEP plants in operation with an installed capacity of 5,175 MW. It is currently undertaking construction of 11 HEP plants with a total installed capacity of 4,622 MW and 8 of these projects totaling 1492 MW are scheduled for completion by the year 2011-12. NHPC generated 16,582 Million Units (MUs) in 2008-09 as against 14,811 MUs in 2007-08.

On consolidated basis, NHPC reported an Operating Income (OI) of Rs 34.94 billion and Profit After Tax (PAT - excluding minority interest) of Rs 12.44 billion in 2008-09 as against an OI of Rs 29.31 billion and PAT of Rs 12.07 billion in 2007-08.

NHPC’s projects are located in India’s Northern and North-Eastern regions, which have favorable hydro resources, thereby ensuring sufficient water availability for power generation. There has been comparison between NTPC and NHPC over the valuations but one clear advantage that NHPC has is that its operation does not have fuel requirement unlike NTPC which makes its operating cost very competitive.

Another advantage of NHPC is that not only are its plants located in High energy deficit areas which ensures consistent demand, NHPC sale of Electricity is backed by LC’s from banks which can be used in case of delay in payments. Further, it is supported by a tripartite agreement between the customer state,RBI and GoI, whereby NHPC can recover the payments from the central plan assistance given to the state by GoI. As a result of these measures, NHPC, for the last few years has reported almost 100% collections against the billing to the respective states.

On the Risk aspects, NHPC projects have long gestation period and hence the the proposed projects would start operating only from 2010-11 onwards. Talking of the Financials, NHPC ROCE stands at 10.18% and RONW stands at just 6.58% due to its large equity base.

Investment Guru’s overall assessment is that NHPC is a stock which may provide good returns over long term (2 Years time frame) based on its fundamentals. The stock may list in the range of Rs. 39-42 and may remain in this range from short term perspective.

Update: NHPC is going to list on NSE and BSE on Tuesday, 1st September,2009

Read More!